IOIPG REIT IPO (5359): IOI City Mall Owner, 6.6% Projected Yield - NOT Shariah Compliant

⚠️ WARNING: This IPO Is NOT Shariah Compliant
IOIPG Malaysia REIT is a conventional REIT, not an Islamic REIT, and its portfolio includes six international hotels. Muslim investors who follow Shariah-compliant investing are advised to avoid this IPO. This article is provided for information only.
IOIPG Malaysia Real Estate Investment Trust (IOIPG REIT, stock code 5359) opened its IPO on 3 November 2026 at a maximum retail price of RM0.96 per unit. Sponsored by IOI Properties Group Berhad (IOIPG), the REIT is scheduled to list on the Main Market of Bursa Malaysia on 25 November 2026. With 5.5 billion units, the fund is worth about RM5.28 billion at the retail price, making it one of the largest REIT listings on Bursa in years.
Its anchor asset is easy to recognise: IOI City Mall in Putrajaya, Malaysia's largest shopping centre. Alongside it are six hotels, including W Kuala Lumpur and Putrajaya Marriott, plus two office towers. This article summarises the key facts from the official prospectus dated 3 November 2026: offer details, unit allocation, property portfolio, distribution projection, strengths and the risks you need to understand.
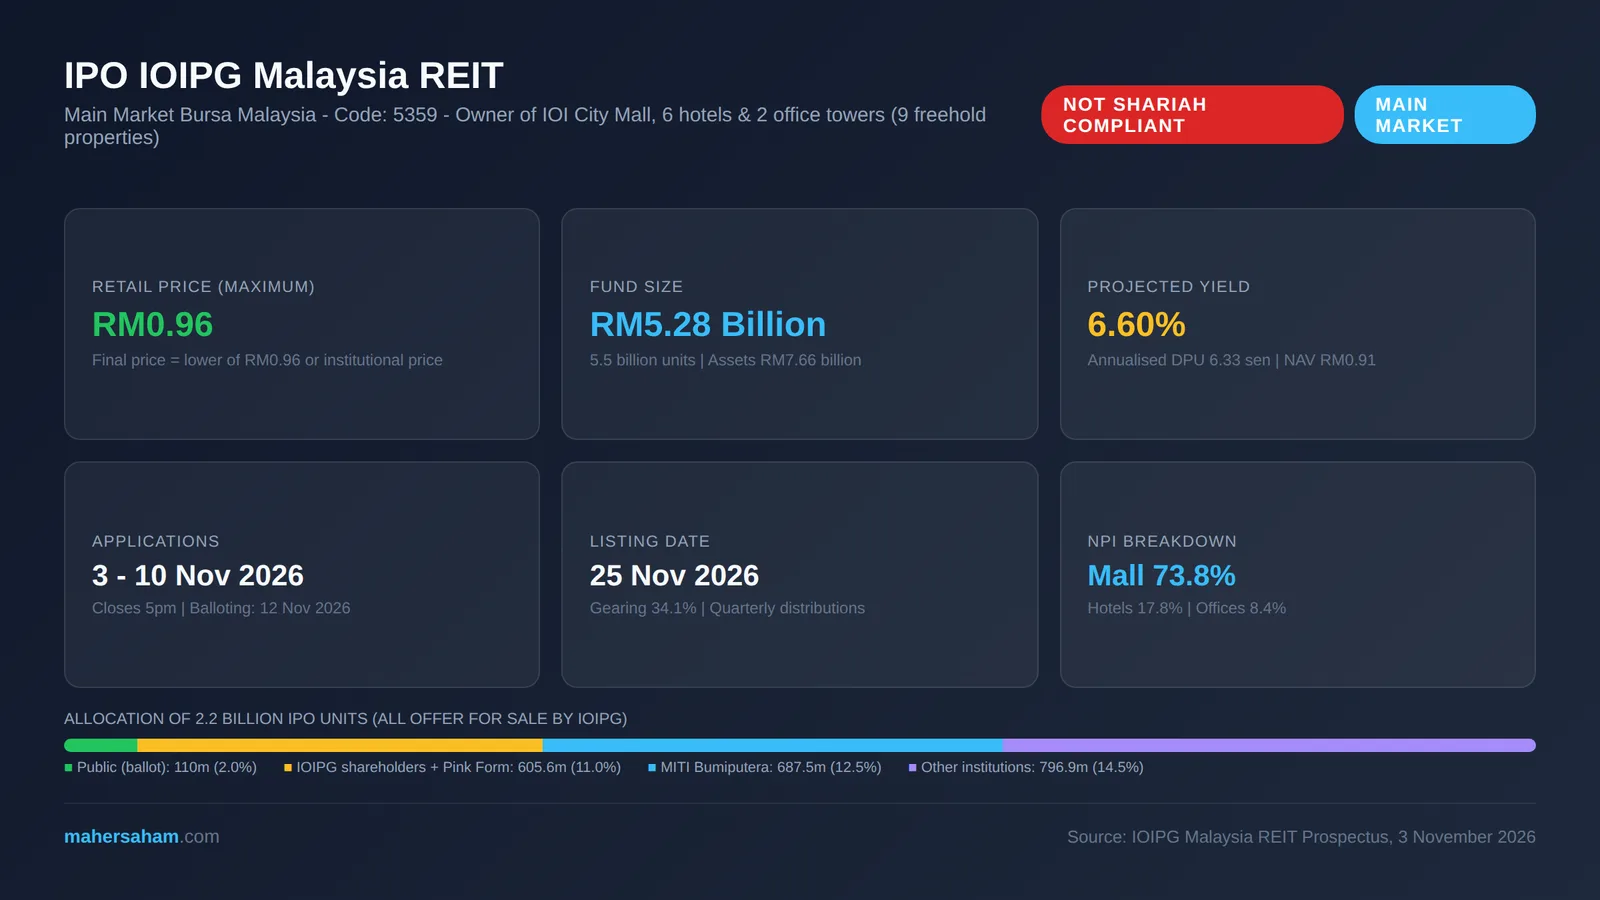
Quick summary: Maximum retail price RM0.96 | Fund size RM5.28 billion | Projected distribution yield 6.60% | NAV RM0.91 per unit | Gearing 34.1% | NOT Shariah compliant | Applications close 5pm, 10 November 2026 | Balloting 12 November | Listing 25 November 2026. View IPO data →
What Is IOIPG REIT?
A REIT (Real Estate Investment Trust) is a fund that owns income-producing property and pays out most of its income to unitholders. If the concept is new to you, start with how REITs let you own property through Bursa Malaysia.
IOIPG REIT was established on 11 September 2026. It will acquire 9 freehold properties from the IOIPG group, appraised at RM7.66 billion as at 31 May 2026. The total purchase price is RM7.58 billion, slightly below appraised value. It is paid with 5.5 billion new units (Consideration Units) issued to IOIPG, plus about RM2.65 billion of borrowings.
The parties involved:
- Sponsor: IOI Properties Group Berhad, a property developer with a market cap of about RM19.27 billion
- Manager: IOIPG REIT Management Sdn Bhd
- Trustee: MTrustee Berhad
- Property Manager: Henry Butcher Malaysia (Mont Kiara) Sdn Bhd (mall and offices only)
IOIPG REIT IPO Details
| Item | Details |
|---|---|
| Name | IOIPG Malaysia Real Estate Investment Trust |
| Stock Code | 5359 |
| Market | Main Market, Bursa Malaysia |
| Retail Price (maximum) | RM0.96 per unit |
| Final price mechanism | Lower of RM0.96 or the institutional price (bookbuilding). Any difference is refunded |
| Units in Issue After IPO | 5,500,000,000 units |
| Fund Size at RM0.96 | About RM5.28 billion |
| Units Offered | 2,200,000,000 units (40.0%), all an offer for sale by IOIPG |
| Offer Size at RM0.96 | About RM2.11 billion |
| Pro Forma NAV per Unit | RM0.91 (price/NAV about 1.05x) |
| Projected DPU (annualised) | 6.33 sen |
| Projected Distribution Yield | 6.60% at RM0.96 |
| Gearing at Listing | 34.1% (REIT limit: 50%) |
| Distribution Policy | At least 90% of distributable income, quarterly |
| Application Period | 3 November (10am) to 10 November 2026 (5pm) |
| Price Determination & Balloting | 12 November 2026 |
| Allotment | 24 November 2026 |
| Listing Date | 25 November 2026 |
| Joint Principal Advisers | Maybank IB, AmInvestment Bank |
| Issuing House | Malaysian Issuing House Sdn Bhd |
| Shariah Status | NOT Shariah Compliant (conventional REIT) |
One key point: IOIPG REIT itself receives no money from this IPO. All 2.2 billion units on offer belong to IOIPG and are being sold to investors. The roughly RM2.11 billion in proceeds goes to the sponsor, not the REIT. Listing costs of about RM4.0 million are paid by the REIT from operating income. If that distinction is unclear, read the difference between a public issue and an offer for sale.
On pricing, you apply and pay at RM0.96. The final price is only known on 12 November, after institutional bookbuilding. If institutions set a lower price, you pay that price and the balance is refunded. The final price will not exceed RM0.96.
Allocation of 2.2 billion units
| Category | Units | % of Fund |
|---|---|---|
| Restricted Offer to IOIPG shareholders (1 unit for every 10 IOIPG shares) | 550.6 million | 10.0% |
| Malaysian public (balloting), half reserved for Bumiputera | 110.0 million | 2.0% |
| Pink Form (directors, employees and eligible persons) | 55.0 million | 1.0% |
| MITI-approved Bumiputera investors | 687.5 million | 12.5% |
| Other Malaysian and foreign institutions | 796.9 million | 14.5% |
| Total | 2,200 million | 40.0% |
The public ballot tranche is only 110 million units, or about RM105.6 million. That is small relative to the total offer. IOIPG shareholders on the 30 October 2026 entitlement date get a dedicated allocation of 1 unit for every 10 shares held. An over-allotment (greenshoe) option of up to 330 million units may also be used to stabilise the price in the first 30 days.
The 9-Property Portfolio: What Does It Own?
| Property | Location | Value (RM million) | Occupancy FPE 2026 |
|---|---|---|---|
| IOI City Mall (Phases 1 & 2 + car parks) | IOI Resort City, Putrajaya | 5,150 | 96.9% |
| W Kuala Lumpur | KL City Centre | 391 | 78.8% |
| Le Méridien Putrajaya | IOI Resort City | 343 | 81.1% |
| Putrajaya Marriott Hotel | IOI Resort City | 266 | 57.4% |
| Moxy Putrajaya | IOI Resort City | 222 | 68.7% |
| Courtyard by Marriott Penang | George Town, Penang | 166 | 78.5% |
| Four Points by Sheraton Puchong | Bandar Puteri Puchong | 128 | 69.1% |
| IOI City Towers | IOI Resort City | 551 | 61.0% |
| PFCC Towers | Bandar Puteri Puchong | 447 | 74.1% |
| Total | 7,664 |
By sector, the mall makes up 67.2% of portfolio value, hotels 19.8% and offices 13.0%. By net property income (NPI) for the FPE 31 May 2026, the mall contributes about 73.8%, hotels 17.8% and offices 8.4%. Around 93% of portfolio value sits in Selangor and Putrajaya.
IOI City Mall: the heart of the REIT
According to the independent property market report in the prospectus, IOI City Mall is Malaysia's largest shopping centre, with 2.58 million sq ft of net lettable area (NLA), more than 850 tenants and 13,987 car park bays. Occupancy has stayed above 95% for the past six years, except in FYE 2023 when Phase 2 had just opened. Mall revenue rose from RM320.9 million (FYE 2023) to RM447.2 million (FYE 2025).
Hotels: guaranteed rent with upside
All six hotels run under Marriott International brands and are leased to IOIPG subsidiaries under master lease agreements. The REIT receives the higher of a fixed monthly guaranteed rent or a variable rent (90% of the hotel's net gross operating profit). This protects income when hotels perform poorly and shares the upside when they do well.
Offices: occupancy still recovering
Offices are the weakest segment. Average occupancy at IOI City Towers and PFCC Towers was 67.1% for FPE 2026, though up from 38.3% in FYE 2023. The weighted average lease expiry (WALE) for the offices is only about 2.08 years.
Financial Performance and Distribution Projection
The figures below are pro forma, meaning they assume all 9 properties were owned by the REIT throughout each period.
| RM million | FYE 2023 | FYE 2024 | FYE 2025 | FPE May 2026 (11 months) |
|---|---|---|---|---|
| Total Revenue | 392.4 | 490.4 | 581.0 | 580.9 |
| NPI | 243.0 | 321.5 | 388.1 | 408.2 |
| Profit After Tax | 877.0 | 974.5 | 1,192.9 | 927.9 |
| Distributable Income | 140.9 | 213.6 | 269.6 | 298.5 |
Note the gap between profit and distributable income. Most of the large profit comes from fair value gains on the properties (for example RM939.6 million in FYE 2025), which are paper gains, not cash. For REIT investors, the number that matters is distributable income, because that is what funds distributions.
For the first projection period (11 September 2026 to 30 June 2027), the manager projects distributable income of RM280.5 million, equal to a DPU of 5.08 sen over 293 days. Annualised, that is a DPU of 6.33 sen, or a 6.60% distribution yield at RM0.96. The first distribution covers the period from listing to 31 March 2027.
The prospectus itself warns that investors will not receive the full projected DPU. Actual ownership starts on the 25 November listing date, not 11 September, and the price you pay in the market may differ from RM0.96.
Manager's fees
The manager charges a base fee of 0.3% per annum of total asset value and a performance fee of 3.0% of NPI. Half of these fees are assumed to be paid in new units. That slightly dilutes unitholders over time, but leaves more cash available for distribution.
IOIPG REIT Strengths
- A dominant anchor asset: Malaysia's largest mall, near-full occupancy and regional pull across the Putrajaya-Cyberjaya corridor.
- All freehold: no risk from a shrinking land lease.
- Low gearing: 34.1% leaves about RM1.24 billion of extra debt headroom for acquisitions without an immediate equity raise.
- Guaranteed hotel rent: a minimum income floor from six hotels.
- Sponsor pipeline: IOIPG grants a right of first refusal (ROFR) over properties it wants to sell, and Dato' Lee grants preferential rights over certain private assets.
- Priced close to NAV: RM0.96 against NAV of RM0.91, a premium of only about 5.5%.
Risks You Need to Understand
1. Heavy reliance on one mall
IOI City Mall contributes nearly three quarters of NPI. Any disruption, such as a new competing mall, refurbishment works or weaker consumer spending in the Klang Valley, hits distributions directly. The portfolio is also concentrated in one area, IOI Resort City.
2. Dependence on the sponsor
All six hotel lessees are IOIPG subsidiaries, and IOIPG will hold about 60% of the units after the IPO (54% if the greenshoe is fully exercised). Many transactions involve related parties, including hotel rent, mall expansion works and lease renewals. Minority unitholders rely on the manager's governance to keep those terms fair.
3. The office segment is still weak
With 67.1% occupancy and a WALE of about 2 years, office income is exposed to tenants not renewing in a Klang Valley office market that already has excess supply.
4. Interest rate sensitivity
With RM2.65 billion of debt, higher financing rates would reduce distributable income. REIT prices also tend to fall when interest rates rise, because investors can get comparable returns from lower-risk instruments.
5. Projections are not guarantees
The 6.60% yield is an annualised projection, not a historical figure. Hotel rent above the guaranteed floor depends on the tourism recovery, and mall rent depends on tenant renewals.
6. An offer for sale by the sponsor
Every IPO unit is sold by IOIPG. That is a normal structure for a sponsored REIT, but it means investor money is not used to grow the REIT. Instead, it helps the sponsor recycle capital out of mature properties.
Why Is IOIPG REIT Not Shariah Compliant?
The prospectus says the REIT's financing is raised through a Sukuk programme and Shariah-compliant facilities. However, the REIT itself is not structured as an Islamic REIT. Its portfolio includes six international hotels, which typically carry non-permissible activities such as serving alcoholic beverages. It is also not on the Securities Commission Shariah Advisory Council list.
Investors who want Shariah-compliant property exposure on Bursa can look at long-listed Islamic REITs such as Axis REIT, Al-'Aqar Healthcare REIT and Al-Salam REIT. Always check the latest SC list before investing, because it is updated twice a year, in May and November.
Who Are the Main Unitholders After the IPO?
All 5.5 billion units are first issued to IOIPG as payment for the properties. After selling 2.2 billion units, IOIPG keeps 3.3 billion units (60.0%), or 2.97 billion units (54.0%) if the 330-million-unit greenshoe is fully exercised. The remaining 40% is held by retail investors, MITI-approved Bumiputera investors and institutions. That makes IOIPG REIT a sponsor-controlled REIT.
Frequently Asked Questions (FAQ)
What is the IOIPG REIT IPO price?
The maximum retail price is RM0.96 per unit. The final price is the lower of RM0.96 or the institutional price set on 12 November 2026. The difference is refunded if the final price is lower.
When does the IOIPG REIT IPO close?
Applications open at 10.00am on 3 November 2026 and close at 5.00pm on 10 November 2026. Balloting takes place on 12 November and the units list on 25 November 2026.
Is IOIPG REIT Shariah compliant?
No. It is a conventional REIT that owns international hotels, and it is not on the SC's list of Shariah-compliant securities. Muslim investors can consider Islamic REITs such as Axis REIT or Al-'Aqar Healthcare REIT.
What is the IOIPG REIT distribution yield?
The annualised projected DPU is 6.33 sen, a 6.60% yield at RM0.96. The manager intends to distribute at least 90% of distributable income every quarter, with the first distribution covering the period to 31 March 2027.
Who is eligible for the Restricted Offer?
IOI Properties Group shareholders registered on 30 October 2026 can apply for 1 IOIPG REIT unit for every 10 IOIPG shares held, totalling 550.6 million units.
Conclusion
The IOIPG REIT IPO offers ownership of Malaysia's largest mall plus six hotels and two freehold office towers. It comes with a projected 6.60% yield, low gearing and a price close to NAV. However, income is heavily concentrated in IOI City Mall, the sponsor keeps 60% of the units, and the distribution projection is unproven. Most importantly for Muslim investors, this REIT is not Shariah compliant. Markets are always uncertain, including REIT prices after listing, so base your decision on your own research and risk tolerance.
Before applying for any upcoming IPO, make sure you have an active CDS account.
Open a CDS Trading Account to invest on Bursa Malaysia as well as foreign markets such as US and Hong Kong stocks.
Download the free Stock Market Basics Ebook to understand the fundamentals before making any decision.
Disclaimer: This article is for educational purposes only and is not a recommendation to buy or sell any security. Investing involves risk and past performance does not guarantee future returns.